Avoiding foreclosure on New York real estate
As a New York resident, owning property gives you a chance to really make the most of this amazing city. Whether you own the property you live in, use for business, or rent out, you must stay on top of your required payments. Otherwise, you can run the risk of seeing the word that every NY real estate owner wishes to avoid seeing: Foreclosure.
Although NY Governor Kathy Hochul signed a new moratorium for foreclosures in New York until January 15th, 2022, you must file a hardship declaration with your lender. As such, it is better to also be prepared for other ways to avoid the threat of foreclosure on your home. To help you avoid the issue, here are some actionable tips to consider.
Engage in reinstatement
The best thing to do is to try and meet the lender halfway. This requires you to agree to meet all of your current amounts, as well as penalties and fees, by an agreed date. This gives you more time to pay and can allow you to source finance to cover this debt burden. Consider reinstatement as your first port of call if you wish to deal with a New York real estate foreclosure threat.
Consider loan forbearance
Some lenders will also consider going down the route of loan forbearance. This means that the lender reduces or suspends monthly payments for an agreed period. The missed payments are then added to the final total.
If your foreclosure threat is more down to temporary cash flow issues and you have shown a good history of payments before, lenders will consider this. However, if your foreclosure is more down to long-term issues and debt, this might not be possible.
Refinance your property
An effective way of keeping hold of a property that might be foreclosed is to refinance your property. Refinance the mortgage on a New York property can be done by the following government refinance options. This could extend the length of your mortgage, but give you more time to manage the payments in smaller quantities. This is useful if your problem is meeting the exact sum as opposed to any sum, and could be the ideal way to keep your property.
Negotiate a short sale
Another option, though seen as the ‘nuclear option’ is to negotiate what is known as a short sale. Lenders will sometimes agree to a short sale, where your home is sold to a third party for a fair market rate, and the lender takes less than the full value of your debt to satisfy your burden.
For example, you might wish to read into how other real estate owners, such as those in Kansas City, deal with foreclosure. Check out ‘How I avoid Foreclosure in Kansas City’ for further ideas and solutions outside of the NY bubble for more advice on dealing with foreclosure.
This is probably the last resort, but it’s an option worth considering should your situation worsen.
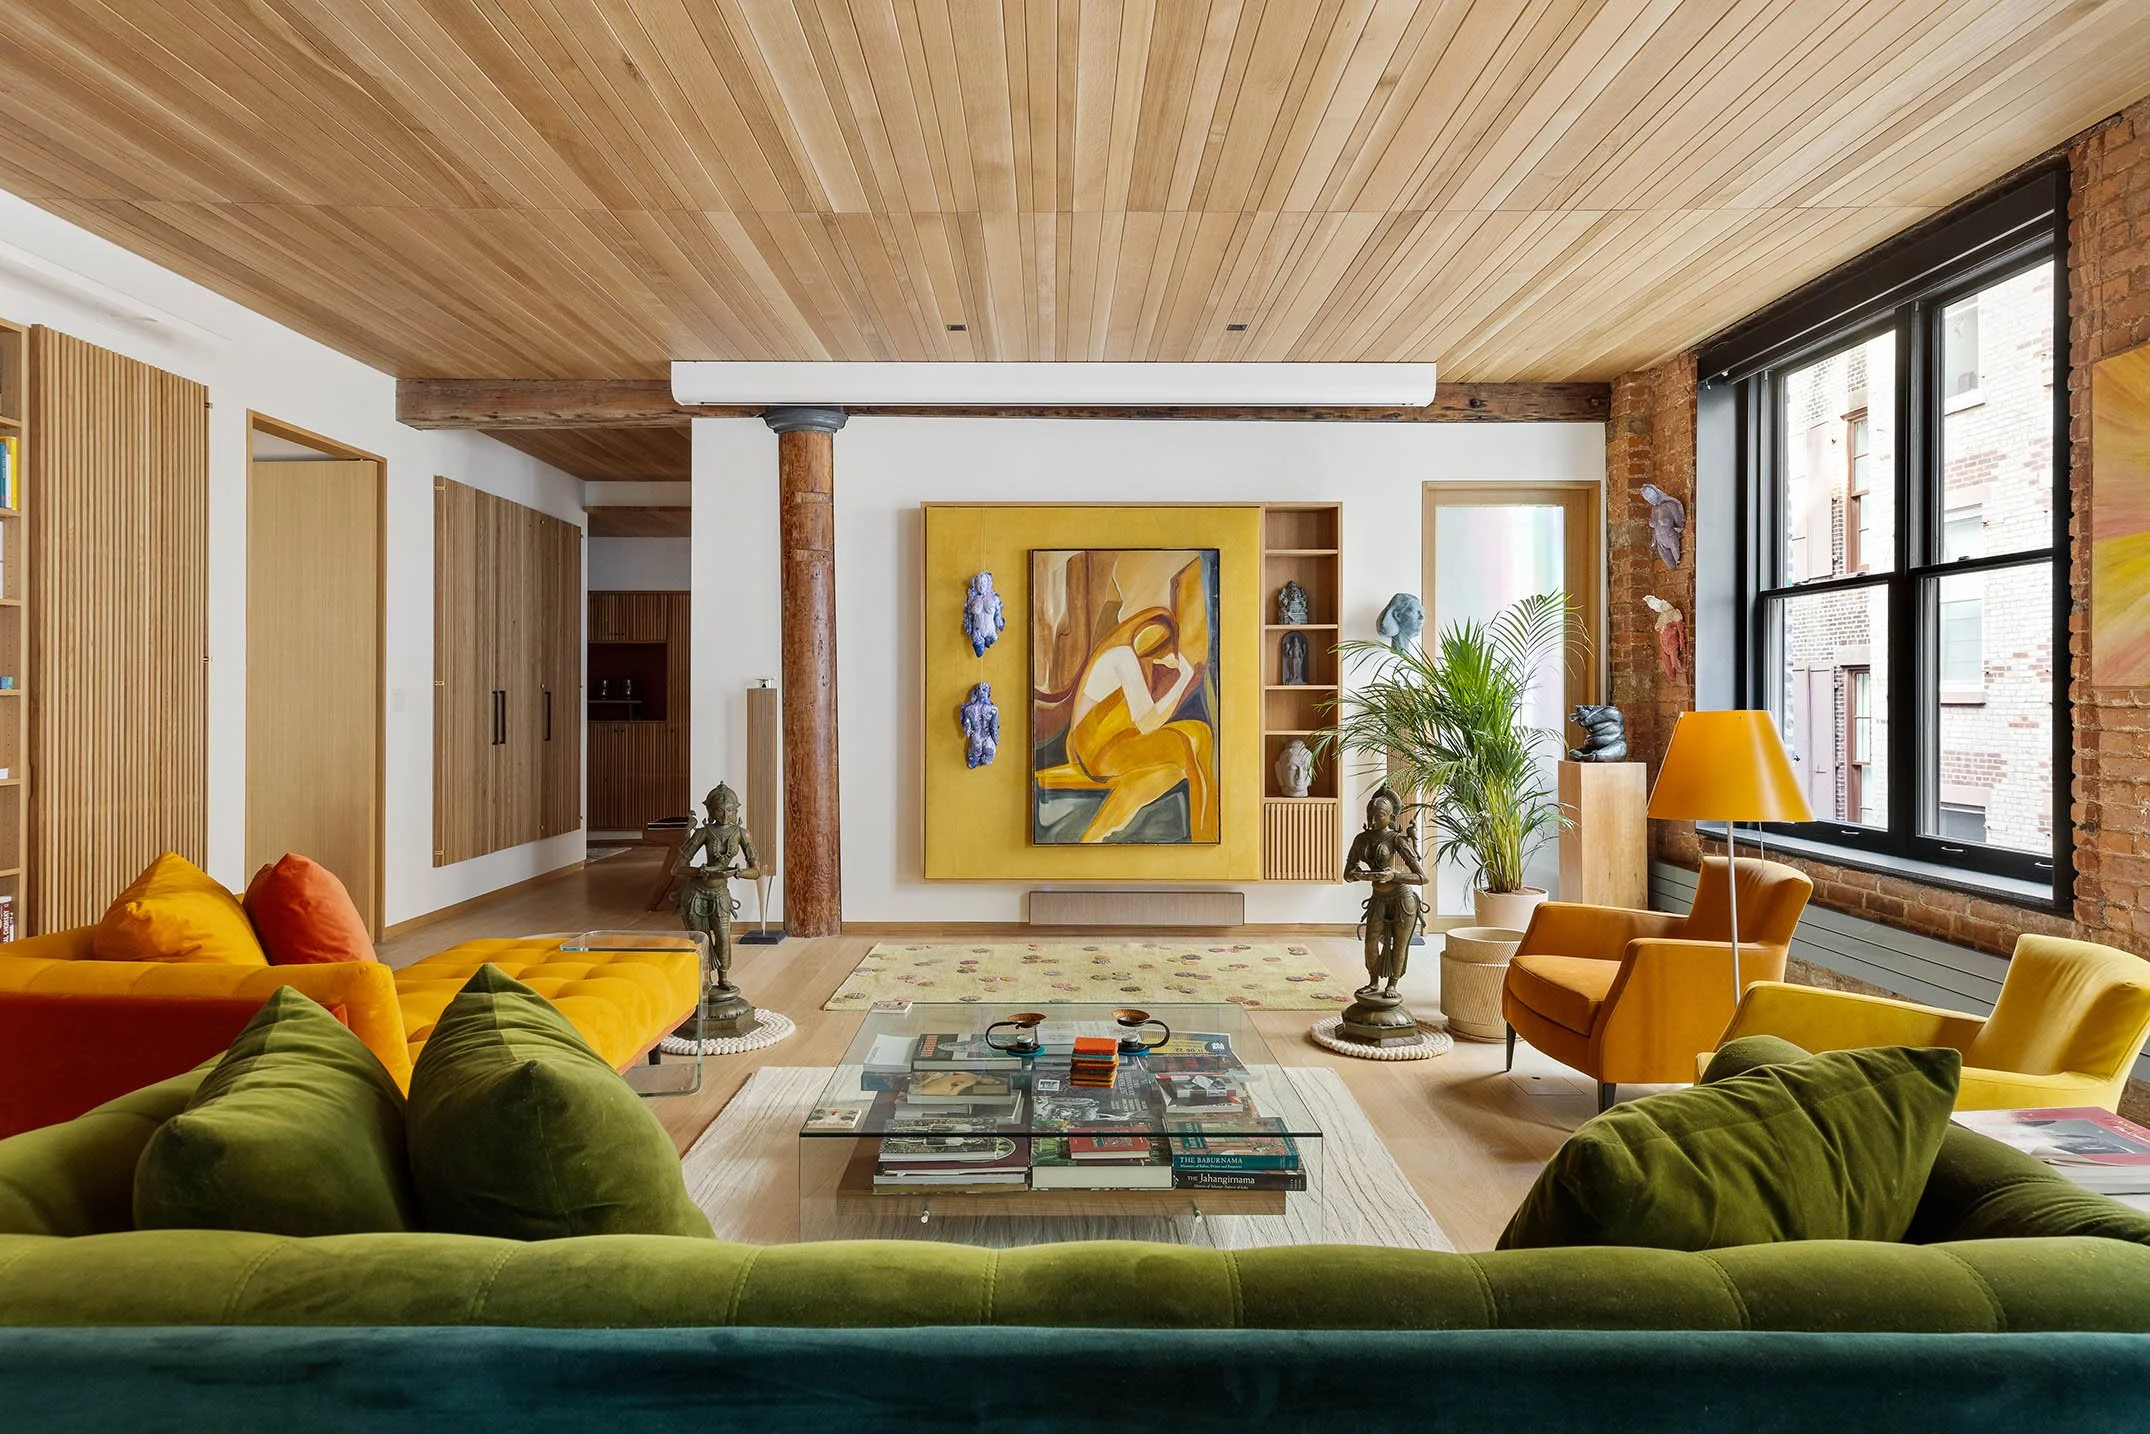
Andrew Franz Architect has reimagined a 2,614-square-foot loft at 50 Wooster Street in SoHo, pairing a 1895 cast-iron building’s original details with custom millwork, a 32-foot great room and a spa-like primary suite.
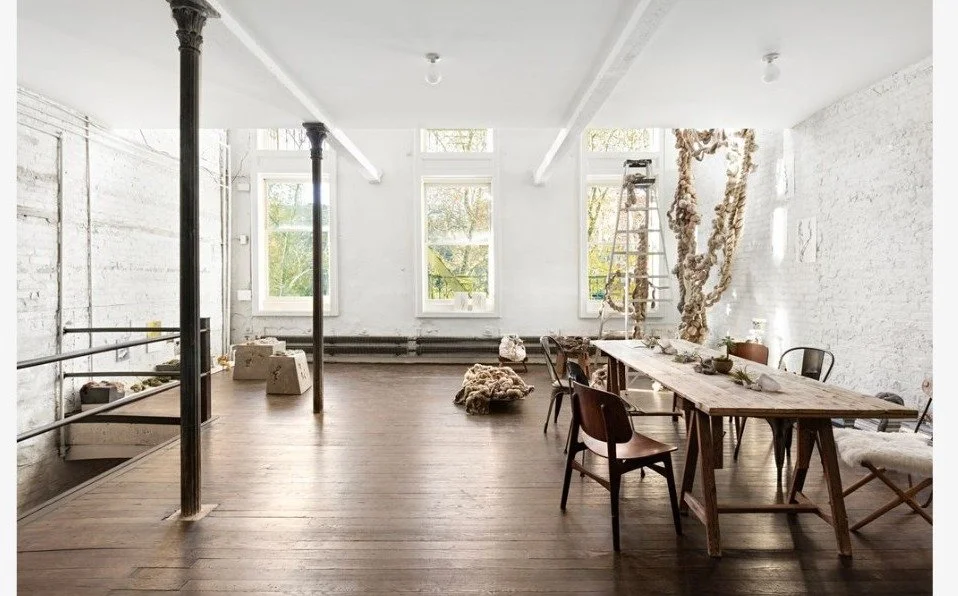
Dive into the details of these remarkable spaces and discover what makes them stand out in the world of real estate.
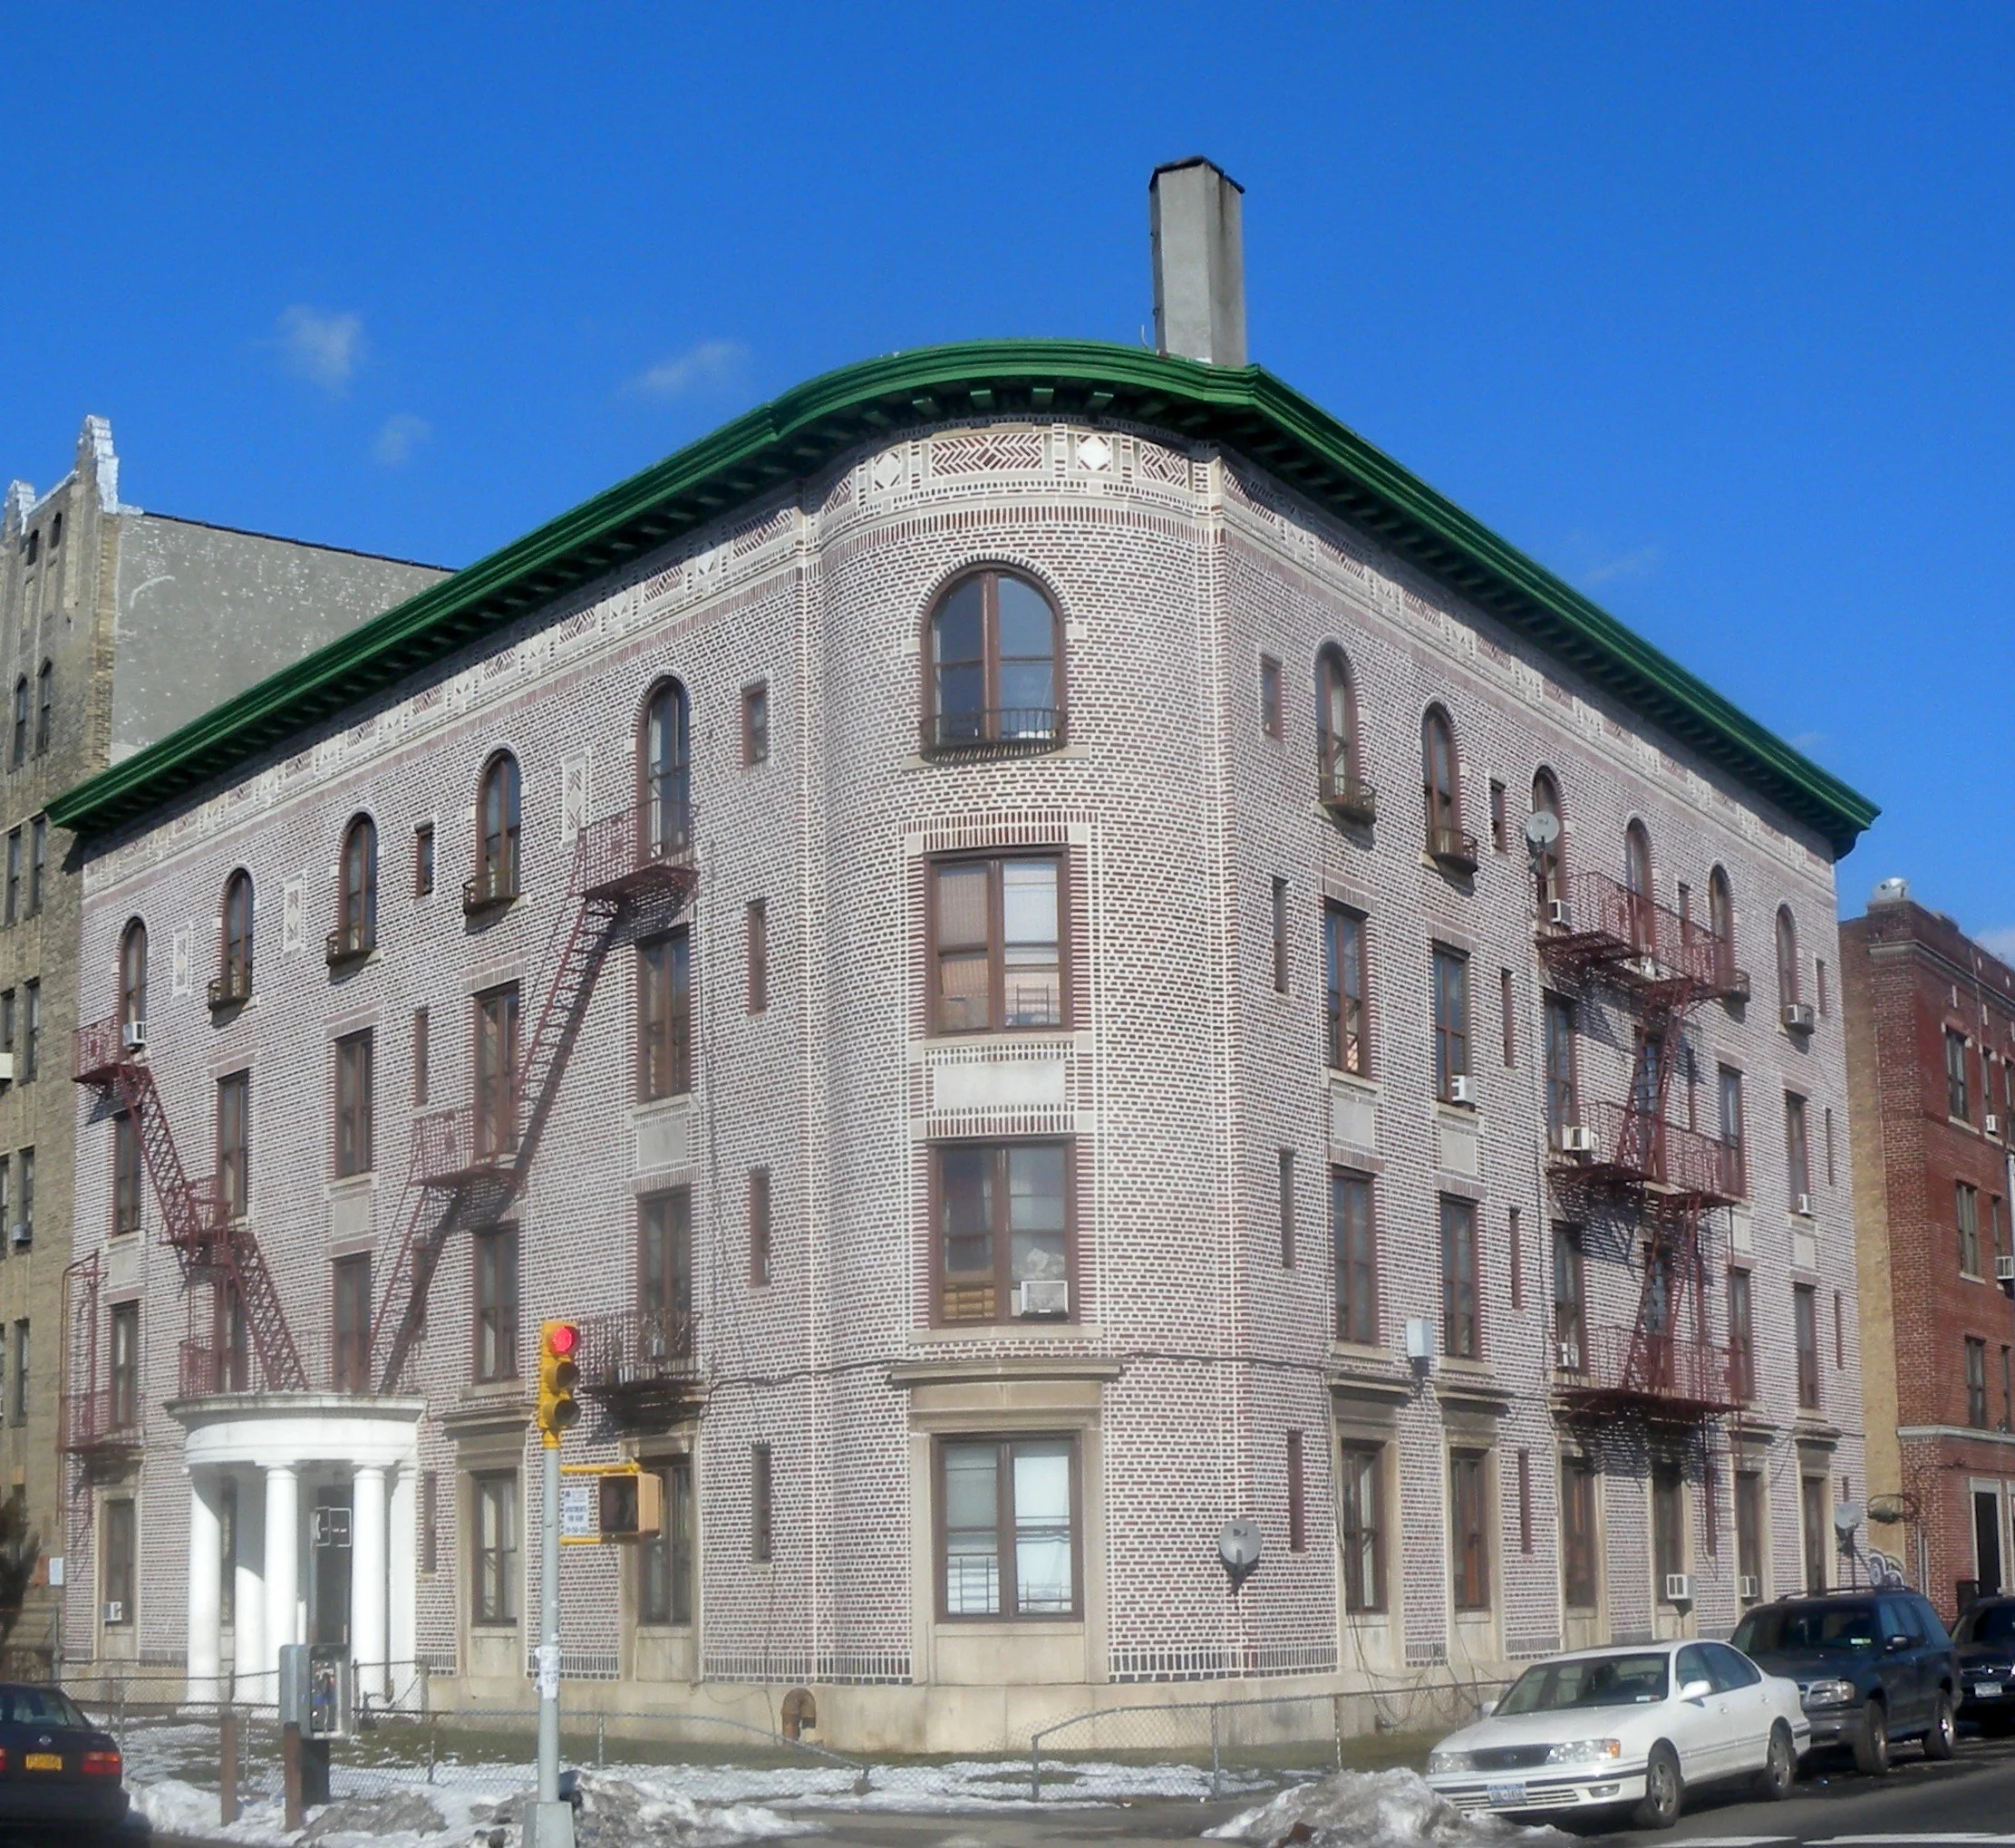
NYC’s latest permit report points to smaller proposed buildings. Explore what that shift means for neighborhood streets, housing choice, and future supply.
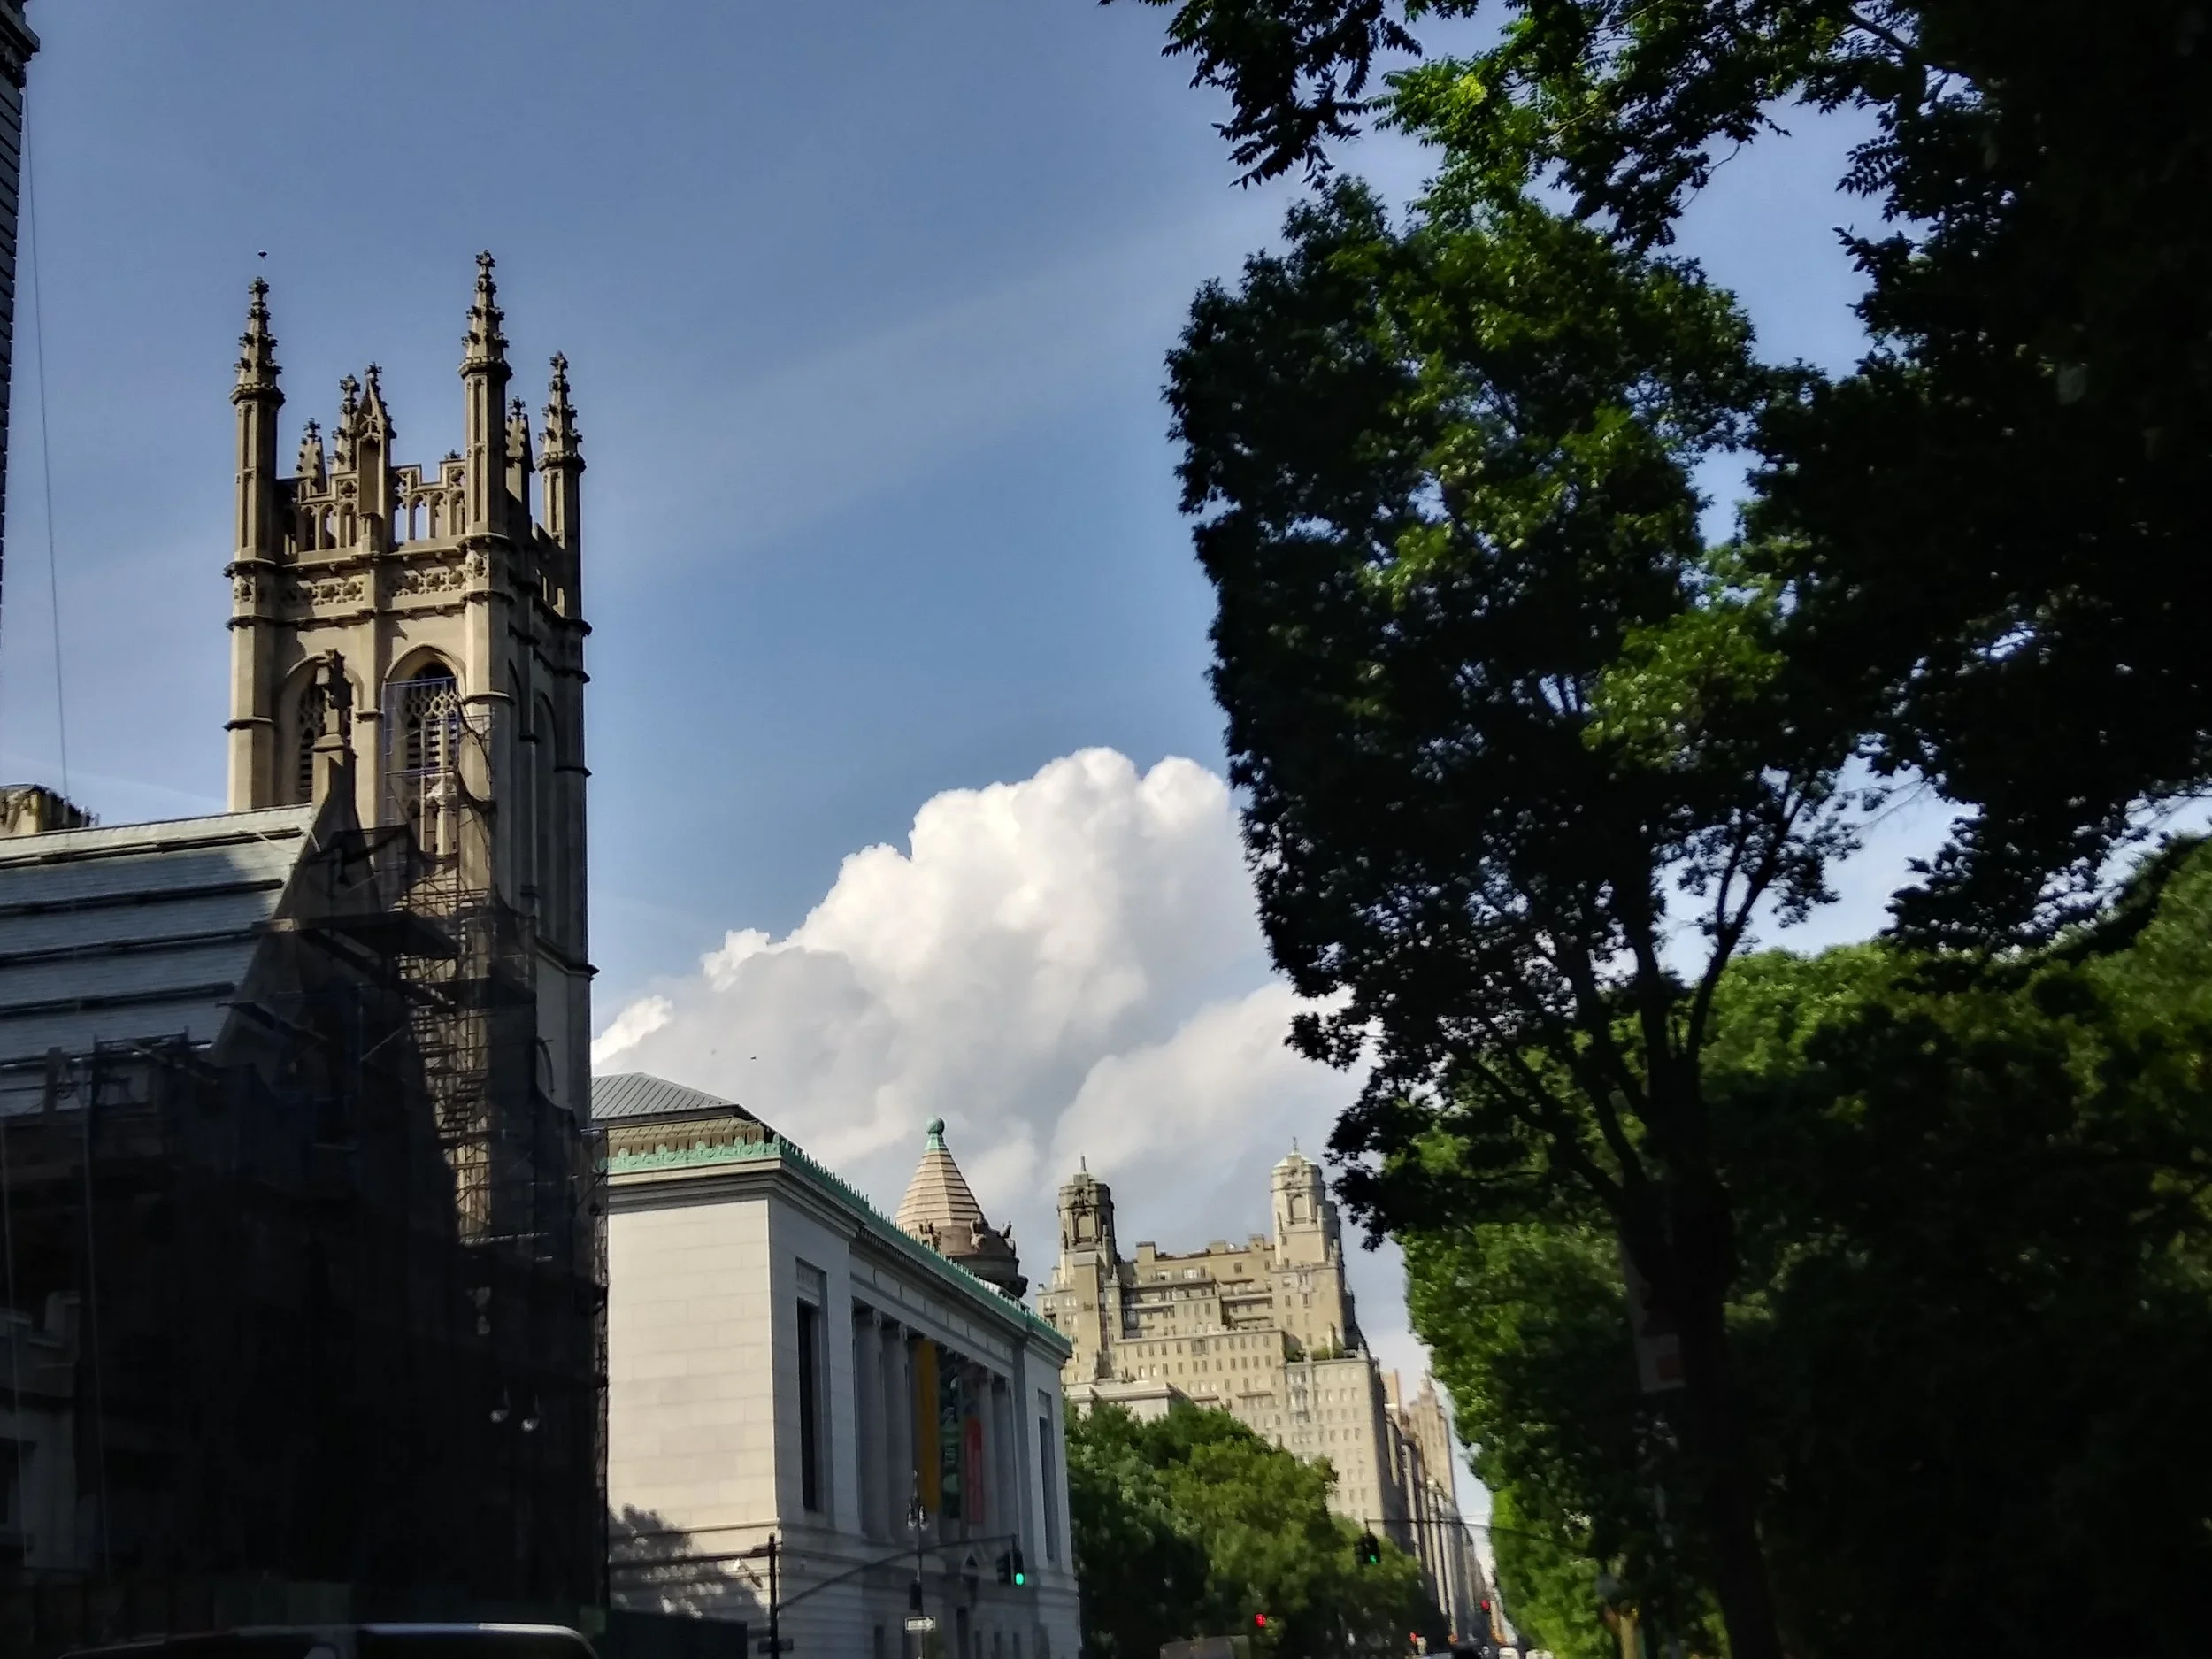
Manhattan studio rents averaged a record $4,186 in August. Explore the cost of living alone, shrinking rental inventory, and the trade-offs behind the price.

Step inside a stunning SoHo loft featured on Open House TV that redefines open-concept living with soaring ceilings, sun-drenched interiors, and modern design details in one of Manhattan’s most coveted neighborhoods.



Carnegie Deli reopens on September 15 at 834 Seventh Avenue, bringing back its towering sandwiches, cheesecake and legendary Wall of Fame just blocks from where it began in 1937.