A First-Time Property Investor’s Guide to Buying Across Australia
First-time investors often treat Australia as one market. It isn’t. The right loan, buffer and suburb choice in Brisbane can be the wrong choice in Melbourne, so investors buying property Australia-wide need to adjust their approach for each state.
Forget one national market
Every state sets its own stamp duty rates and land tax thresholds. Tenancy laws and planning rules also change at the border. What looks affordable in one capital can carry much higher holding costs in another.
Rental rules and approval timelines are local, so national headlines are a poor substitute for suburb-level research. Rules that apply in Victoria may not apply in Queensland.
Population changes and new infrastructure can shape demand differently from one city to the next. Council zoning and flood or bushfire overlays may also affect what can be built or insured. Review transport projects, employment centres, planning controls and long-term price trends before narrowing the search.
Treat each purchase as a state-specific deal. The paperwork and costs reset every time you cross a border.
Check where each city sits in the cycle
Capital cities don’t necessarily rise and fall together. Employment, migration, housing supply and interest rates can affect each one differently. A slower market may give buyers more time to negotiate, while stronger competition can shorten decision-making time. Neither condition removes the need for careful due diligence.
Instead of asking whether now is a good time to buy in Australia, read local vacancy reports and sales volumes before you travel. Consider where a specific city sits in its own cycle. Then check whether rents and supply support the price you are being asked to pay.
Bring in help when you buy interstate
Buying in your home suburb is one thing. Buying two states away is a different job.
The balance between auctions and private treaty sales differs by location, and sale processes can carry different risks. Conveyancing requirements also vary between states and territories.
A buyer’s agent can help close that gap by investigating local risks, comparing properties and representing the buyer during negotiations. Local knowledge can also help an investor ask better questions about flood exposure, strata records, rental demand and the surrounding streets. Independent building, pest, legal and financial checks are still essential.
Pre-approval matters here. You can’t bid with confidence if your limit is vague.
Investors who want help with the search and negotiation can explore Australian Property Experts (https://australianpropertyexperts.com.au/). Professional support can help buyers assess unfamiliar locations and prepare for negotiations, but the final decision remains with the investor.
Add up the full cost before you commit
New investors often budget for the deposit. They forget the rest.
Some buyers aim for a 20% deposit to avoid Lenders Mortgage Insurance, although requirements depend on the lender, borrower and loan structure. LMI can increase the cost of borrowing without increasing the property’s value, so request a loan-specific estimate rather than relying on a rule of thumb.
Then comes transfer duty. Rates vary by state, property value and buyer circumstances. Do not assume a first-home exemption or concession applies to an investment purchase; check the relevant state or territory revenue office.
Add conveyancing costs on top. Pay for a building and pest inspection too. Those checks are especially important for older houses or properties in termite-prone areas. A good conveyancer can identify easements and title issues before you are committed.
Ongoing costs bite as well. Units bring body corporate or owners corporation fees. States and territories may charge land tax on investment holdings above their applicable thresholds.
There’s no single figure that works everywhere.
Save a buffer for these extras. If the deal only works when every cost comes in low, it doesn’t work. A reasonable buffer can stop one surprise from sinking your first year.
Run the tax and yield maths before you offer
Tax changes the return. Understand the general rules before you sign and seek qualified tax or financial advice for your circumstances.
Depending on your circumstances and current tax rules, negative gearing may allow you to offset a rental loss against other income. That can help cash flow while you wait for growth. It won’t turn a poor property choice into a good one.
Capital gains tax may apply when you sell. Eligible Australian resident individuals who hold an investment for more than 12 months may qualify for a 50% discount on the capital gain under current rules. Shorter holds generally don’t receive that discount.
Then run the yield. Gross yield alone will not tell you the full story. Strata levies, maintenance, management costs and vacancies can materially reduce the return, so calculate an estimated net yield rather than relying on the listing headline.
A cheap price can hide weak rent. Do the weekly maths. If rent does not cover the expected costs, be honest about the size of the shortfall and how long it could be sustained. Tax outcomes should be assessed separately with an appropriately qualified adviser, not used to rescue an otherwise unsuitable purchase.
Start small and keep your homework local even if you buy far away. Let the numbers veto the emotion. Investors who last tend to budget for the state they buy in rather than relying on a national average.
Have a listing you think should be featured contact us or submit here to tell us more! Follow Off The MRKT on Twitter and Instagram, and like us on Facebook.

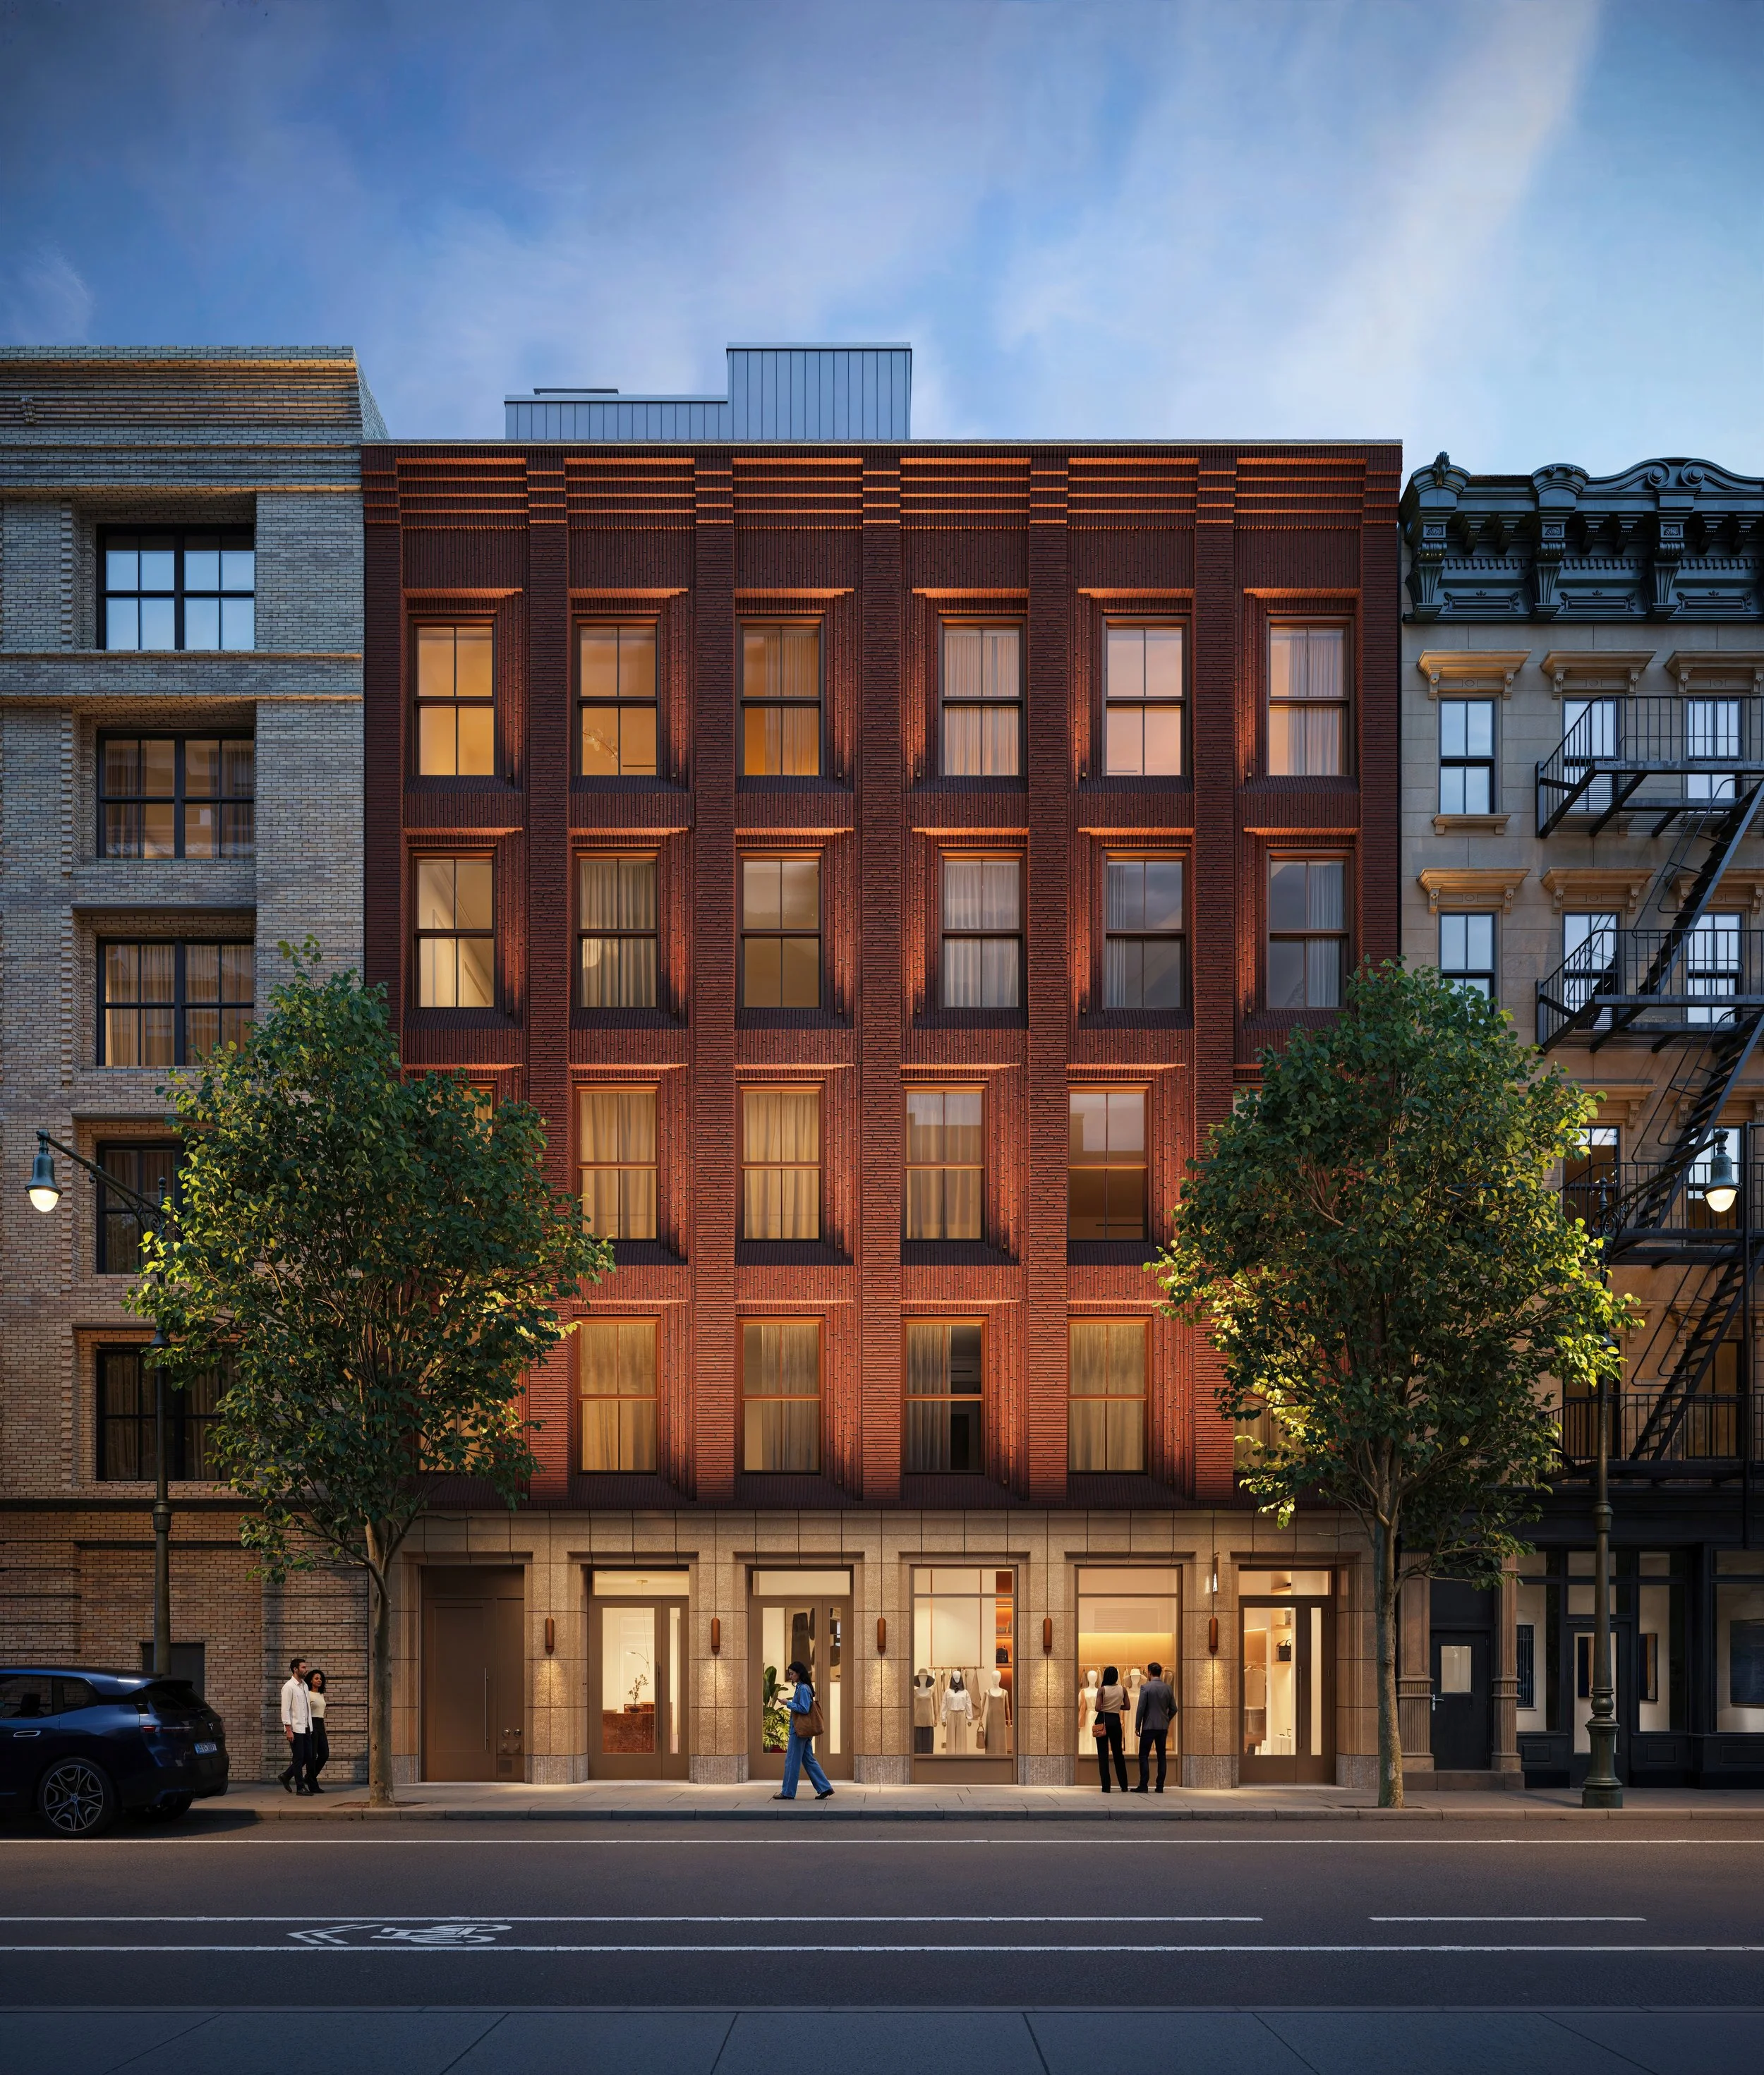
Sales are underway at 44 West 8th Street, a 50-foot-wide, five-residence Greenwich Village condo off Washington Square Park with full-floor homes from $9.75 million.